Porsche AG (P911) – Q3 Shows the Turnaround is Working – But I’m still not buying
Revenue is still falling, China remains weak, and much of the improvement comes from lower charges rather than a clear operational turnaround. In this post I break down what actually happened, why the stock rose anyway, and why I’m still not convinced it’s time to buy.
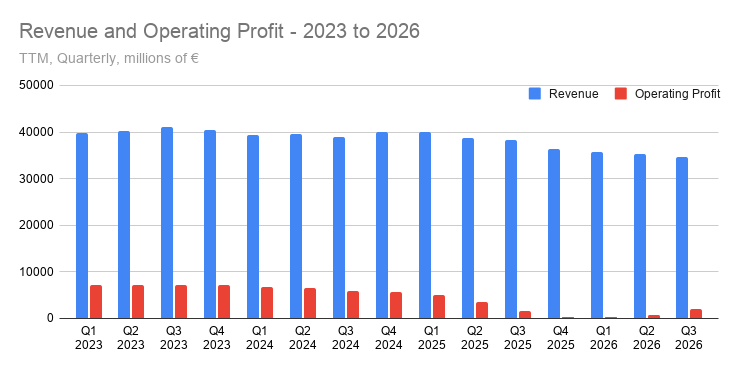
After a rough 2025, which was one of the hardest years in the automotive industry, 2026 is finally looking like there is a possibility of a turnaround. Still, sales revenue declined in comparison with 2025 (Q1–Q3) by a little less than 6%. Unfortunately, quarter-over-quarter doesn’t look good either, with a 7.5% decrease in revenue.
For the first nine months of 2026, Porsche delivered:
- Sales revenue of €25.28 billion (down 5.9%)
- Operating profit of €1.74 billion (up from €40 million)
- Operating return on sales of 6.9% (up from 0.2%)
- Deliveries of 178,532 vehicles (down 16%)
As already noted, in Q3 alone, revenue fell about 7.5% to €8.05 billion and operating profit came in at €387 million with a 4.8% margin.
Still, I need to be precise here. The year-over-year jump in operating profit looks dramatic, but it is very important to understand the context. Last year’s first nine months were crushed by strategic realignment expenses related to the failed electrification push. These charges were not small (around €2.7 billion), and this year charges were closer to €500 million.
What is actually improving?
A basic look at the chart makes it clear that revenue is still not improving. We had a few quarters where we thought the decrease in revenue was finally slowing down, but with this quarter it is clear that we are still not at the bottom.
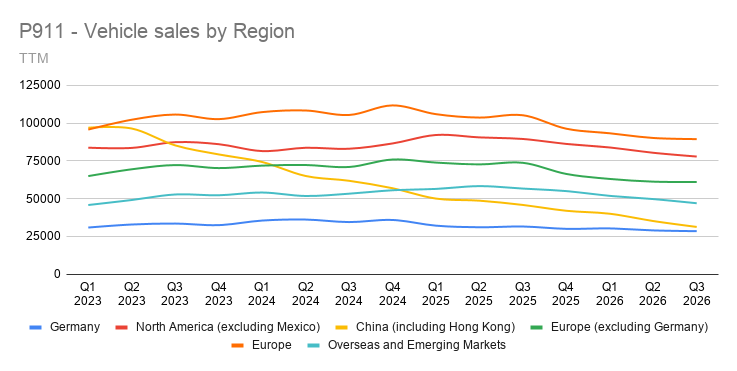
China remains the structural problem. Deliveries there fell from roughly 32,000 (first nine months of 2025) to 21,500 units (same period of 2026). When compared to Q3 2025 (10,893 units sold), this quarter looks very harsh (only 6,992 units sold).
This trend is clearly visible in the graph below. There is no need to explain it any further.
Better product mix/pricing (“Value over Volume”)
The “Value over Volume” approach is something we are hearing very often from European carmakers, but German brands are really pushing this narrative. Porsche has a very strong position in this segment, and it is shown in the numbers. Average selling price increased to €126,000 from €120,000, even as deliveries dropped sharply.
The 911 was the only model with rising sales, with an around 12% increase in the first nine months. While we are talking about units sold per model, it is clear that electrification didn’t bring the results that were expected. We already talked about this, but it is clear from the P911 infographic.
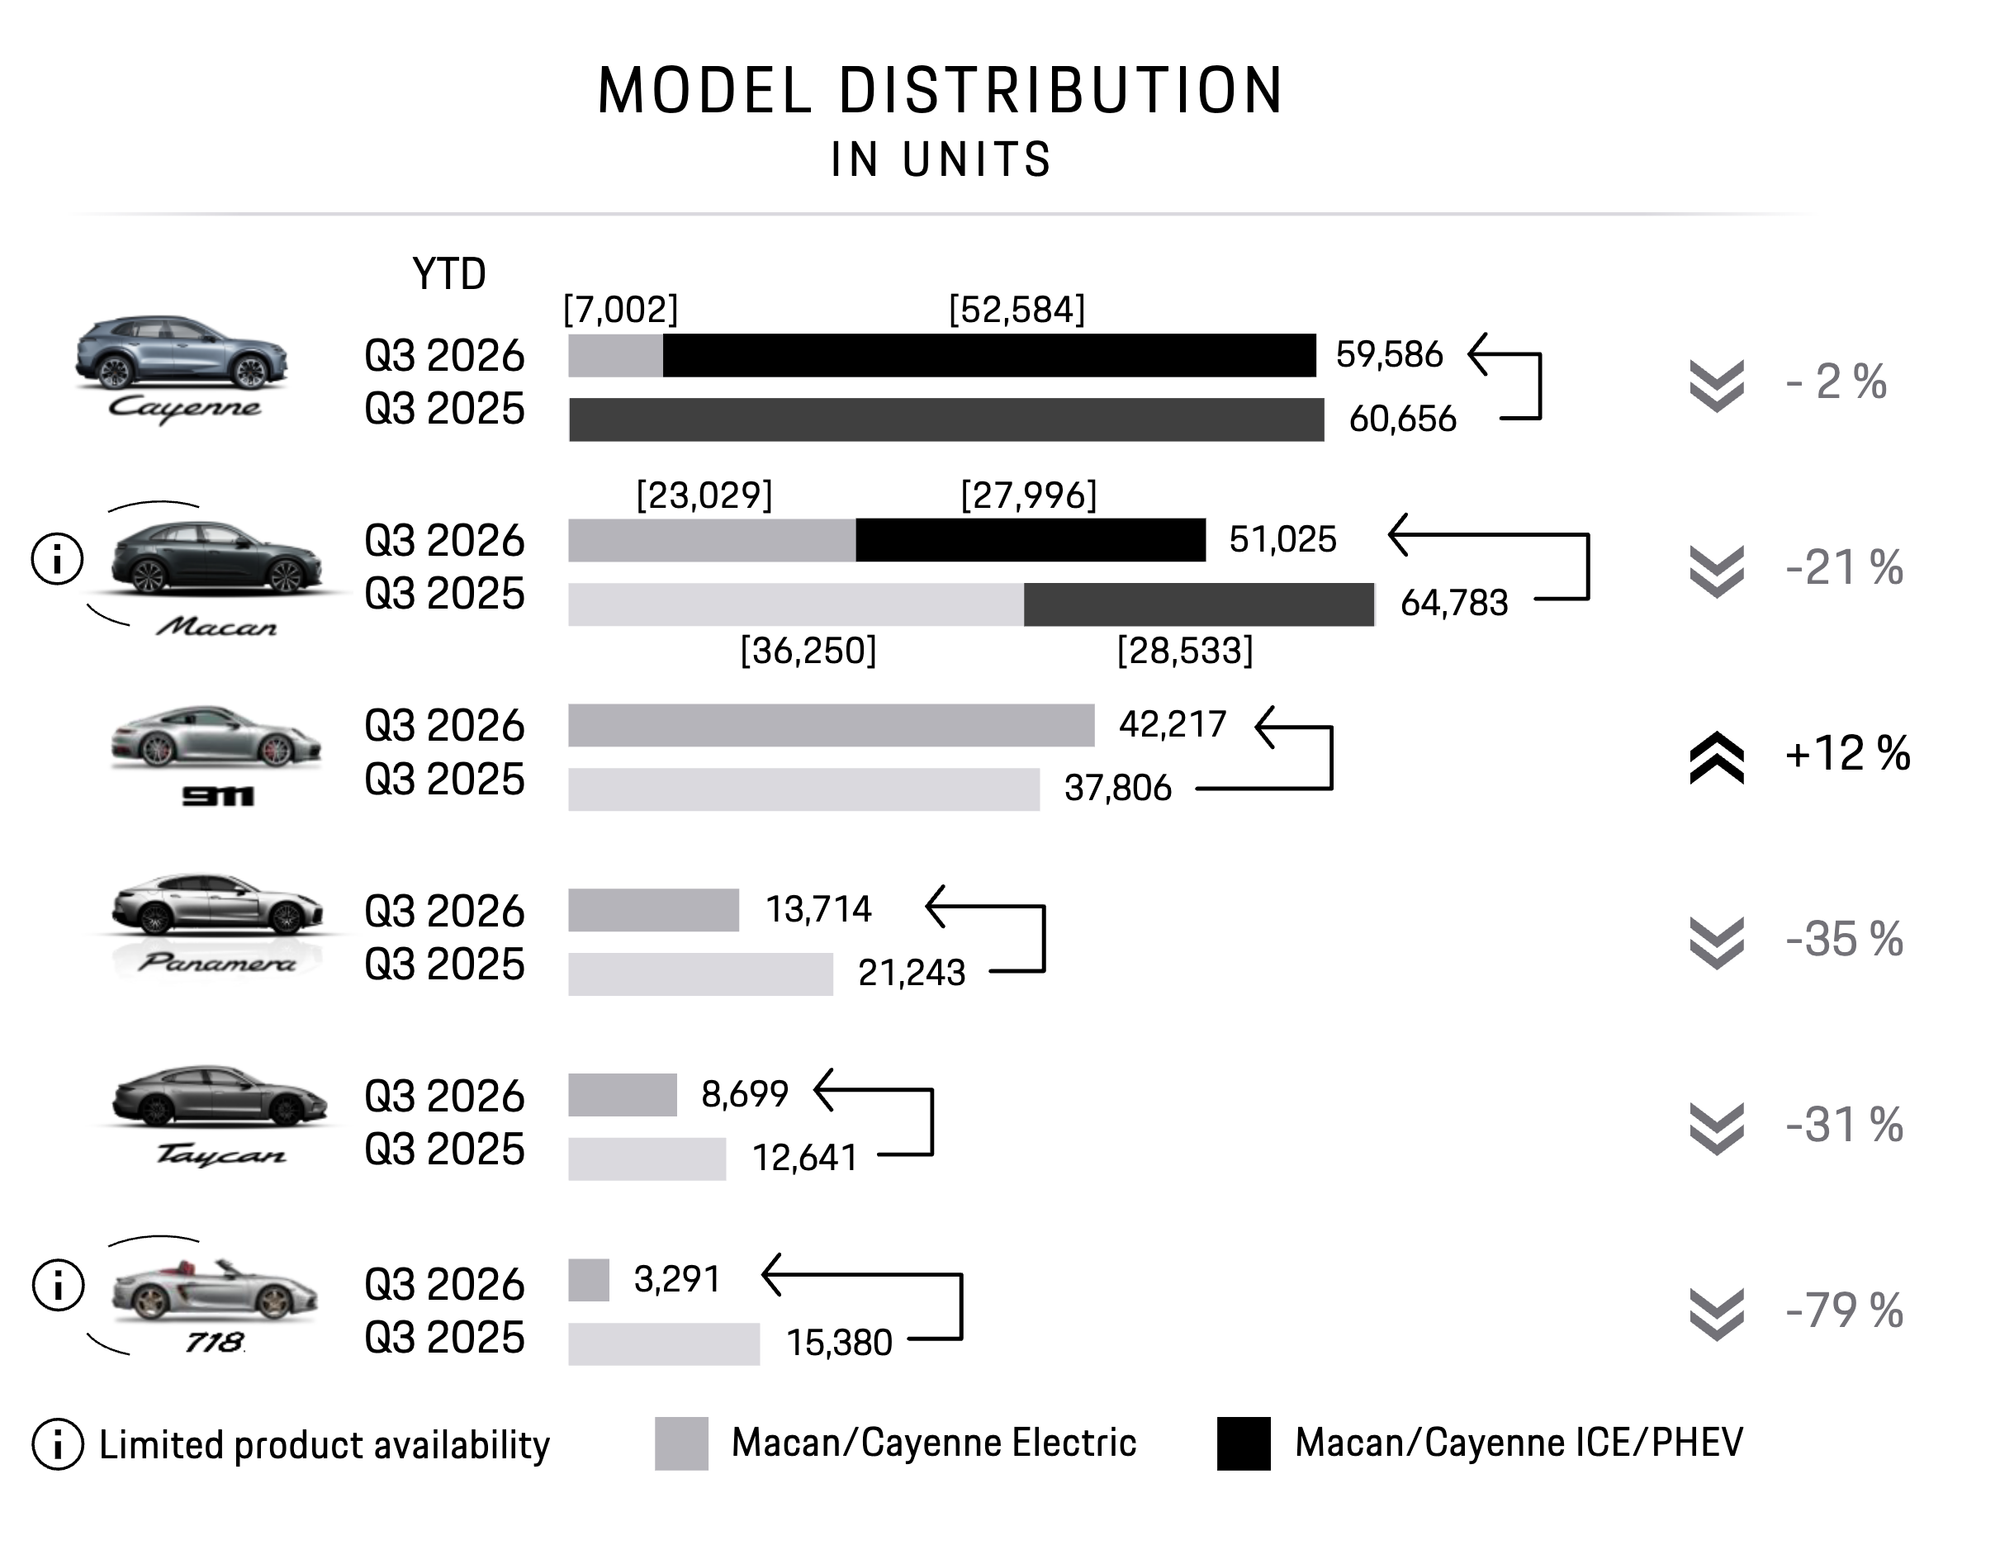
It is worth noting that Porsche completed the sale of its stakes in Bugatti Rimac and the Rimac Group. This was part of its strategic realignment to focus on the core Porsche business.
Why the stock rose anyway
The most important idea behind today’s price increase is that the bar was not set high. A long stretch of weakness and a quarter where it looks like there is no need to decrease expectations is enough to bring a positive outlook on this company. It is worth mentioning that P911 has a forward P/E ratio around 22.86, which is very high in the context of today’s industry (MBG’s forward P/E is around 6).
My take
This quarter is showing progress, but this is still not a healthy company, especially in today’s industry. The brand moat is intact, and I like that CEO Michael Leiters is focusing on core sports cars, with customization and higher-margin models. Still, the numbers are not proving that this model is working at scale.
I would still want to see the stock meaningfully lower or clearer evidence that the “value over volume” strategy is working. For now, this is one to keep watching and maybe sell some puts in the 35 area.
Unfortunately, the next quarter will still not be enough to confirm that a recovery has started. Most probably we will need to wait until the end of 2027 for that.